
Finance that works as hard as you do.
Flexible commercial vehicle & equipment finance, so you can spend more time on the tools.
Finance built for business.
We handle the heavy lifting so you can keep your business moving forward.
FLEXIBILITY
LOW DOC OPTIONS
Many lenders don’t need full tax returns. If you have an active ABN, we can look at low doc options that cut down the paperwork.
EFFICIENCY
WE DO THE HEAVY LIFTING
You are busy running a business, not chasing banks. We handle the heavy lifting, lender negotiations & complex paperwork in the background so you can stay focused on the job site.
ACCESS
SPECIALISED COMMERCIAL LENDERS
Don’t settle for whatever your everyday bank offers. We compare a panel of specialised commercial lenders to find a product & structure that suits your business.
Know your numbers before you buy.
Move the sliders to get a rough weekly figure for your next ute, van, machine or tools. Add a balloon to see how it changes your repayments.
When you’re ready, we’ll compare our panel of commercial lenders and find the right structure for your business.
Gear up for growth.
From your first work ute to an entire heavy machinery fleet, if it helps your business earn, we have lenders that finance it.
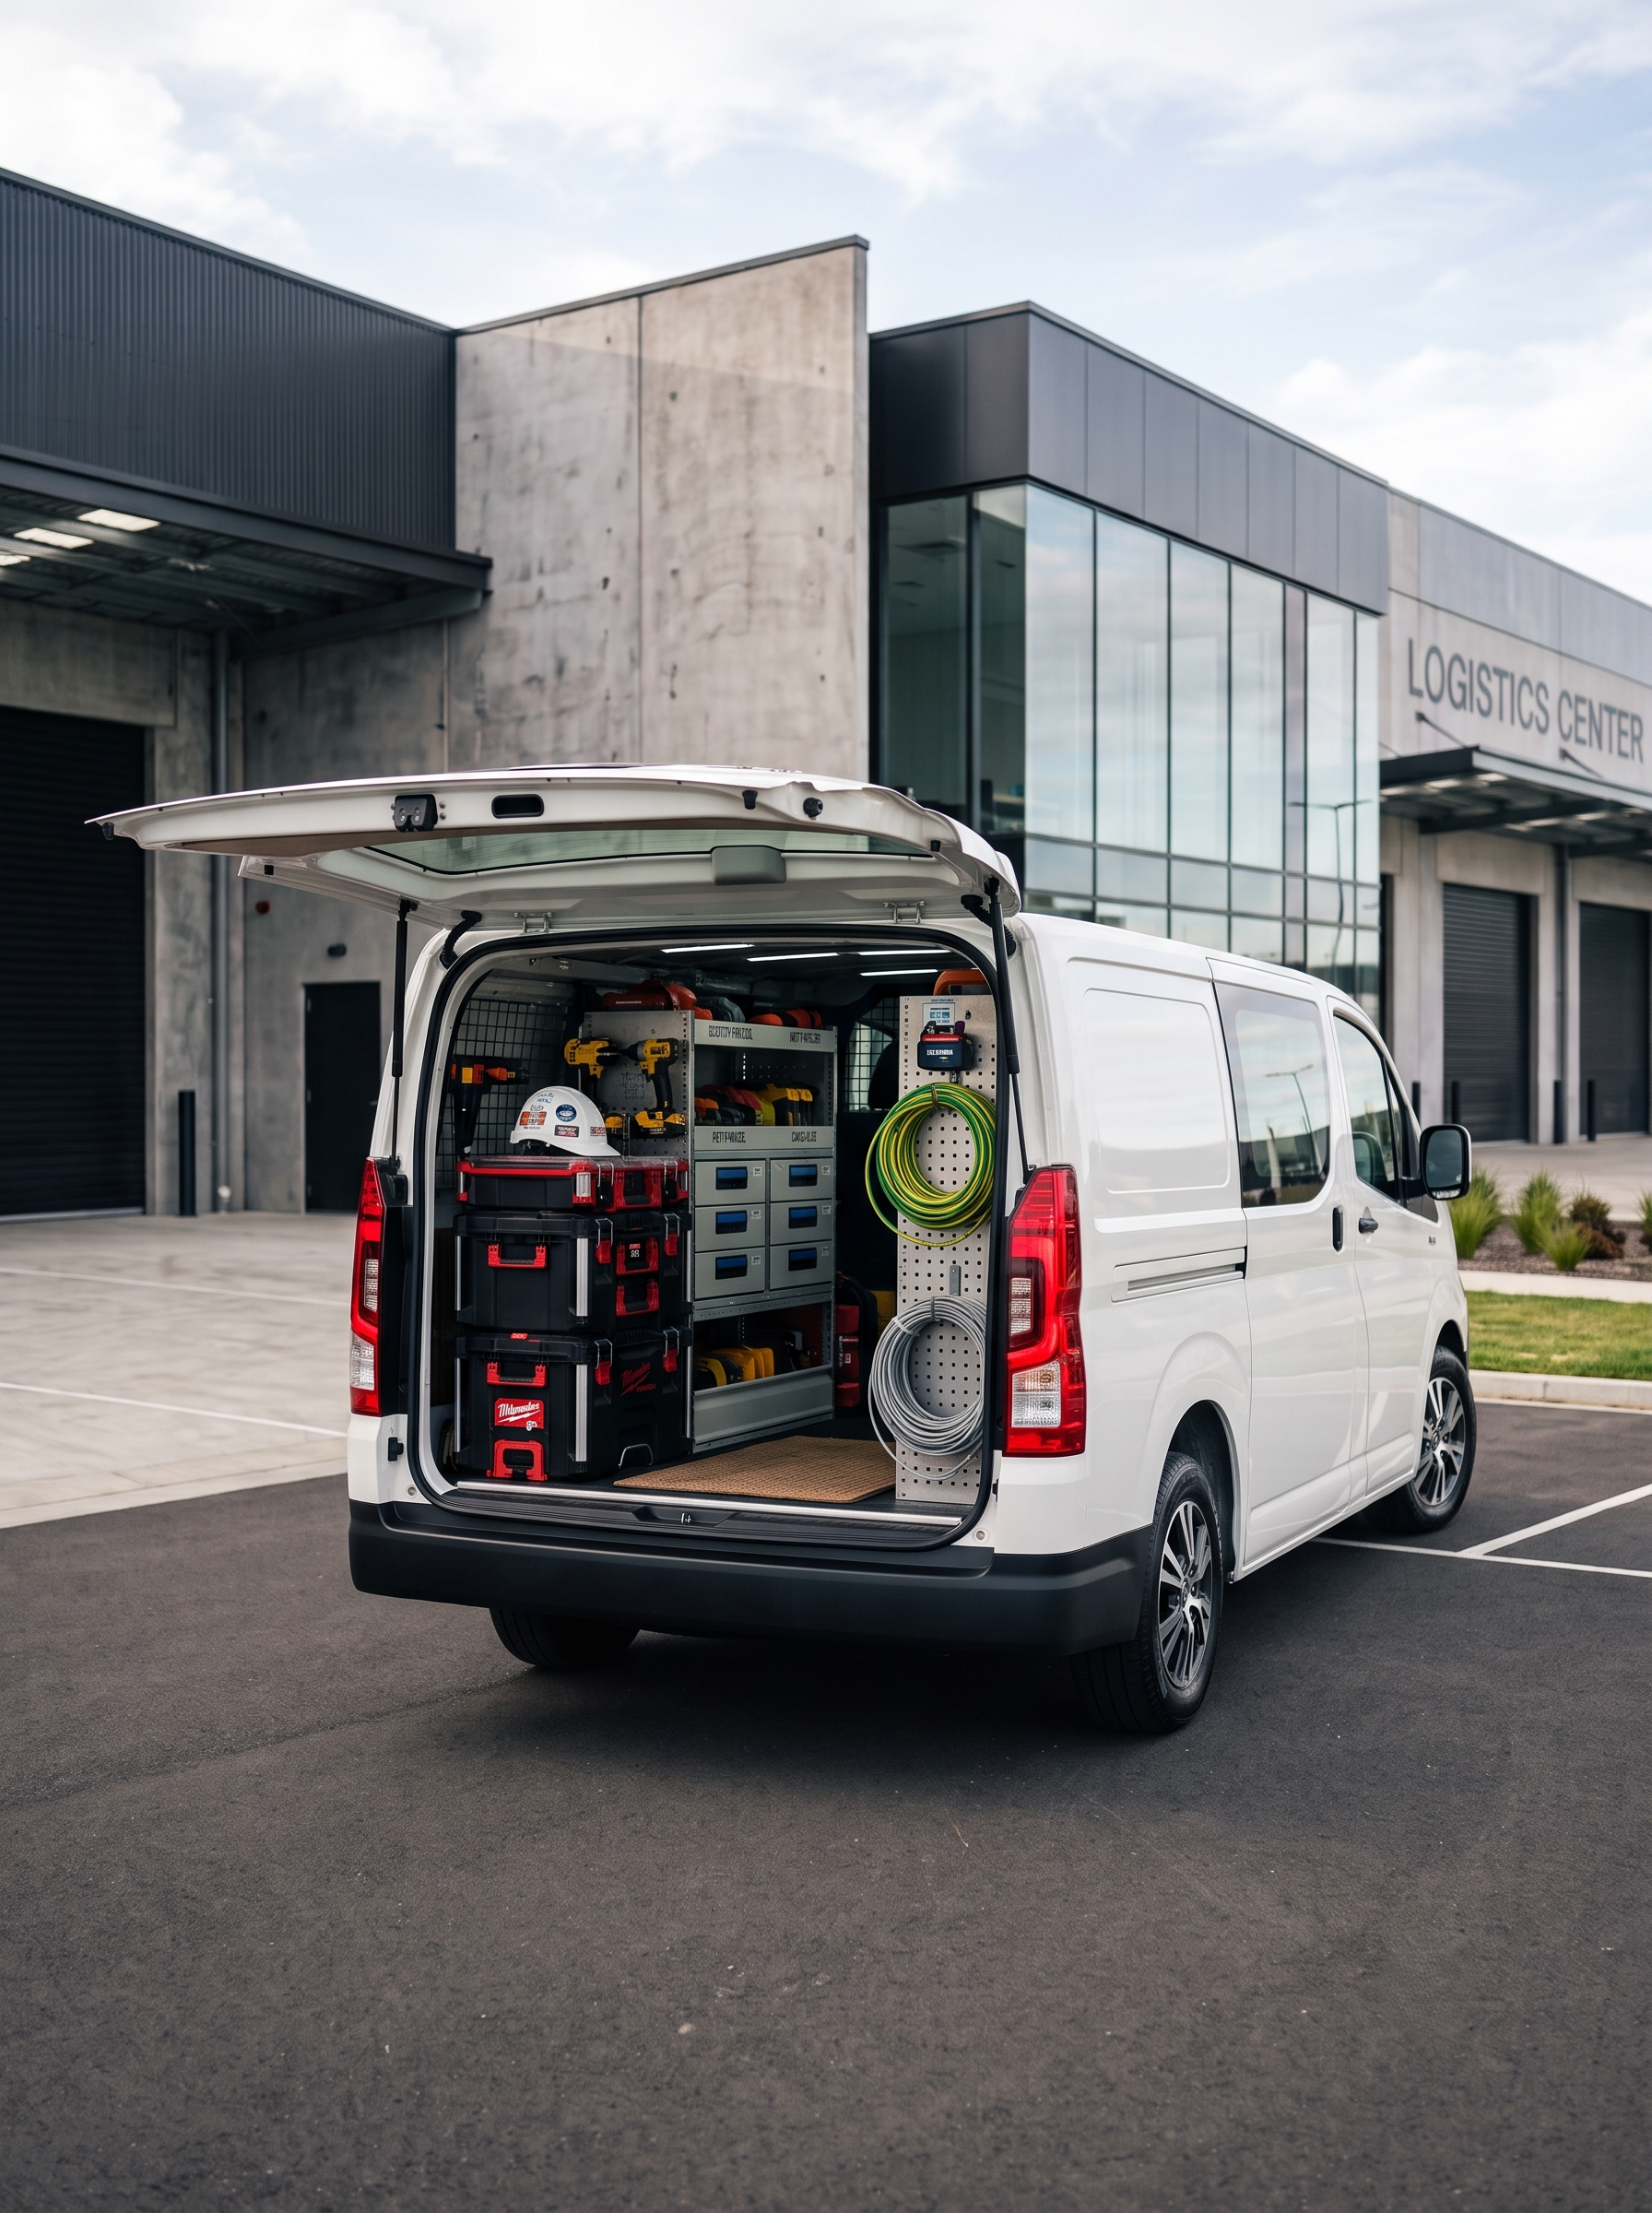
Upgrade your daily drive. We finance individual work vehicles for sole traders up to multi-vehicle fleets for growing companies.
Utes, Vans & Light Trucks
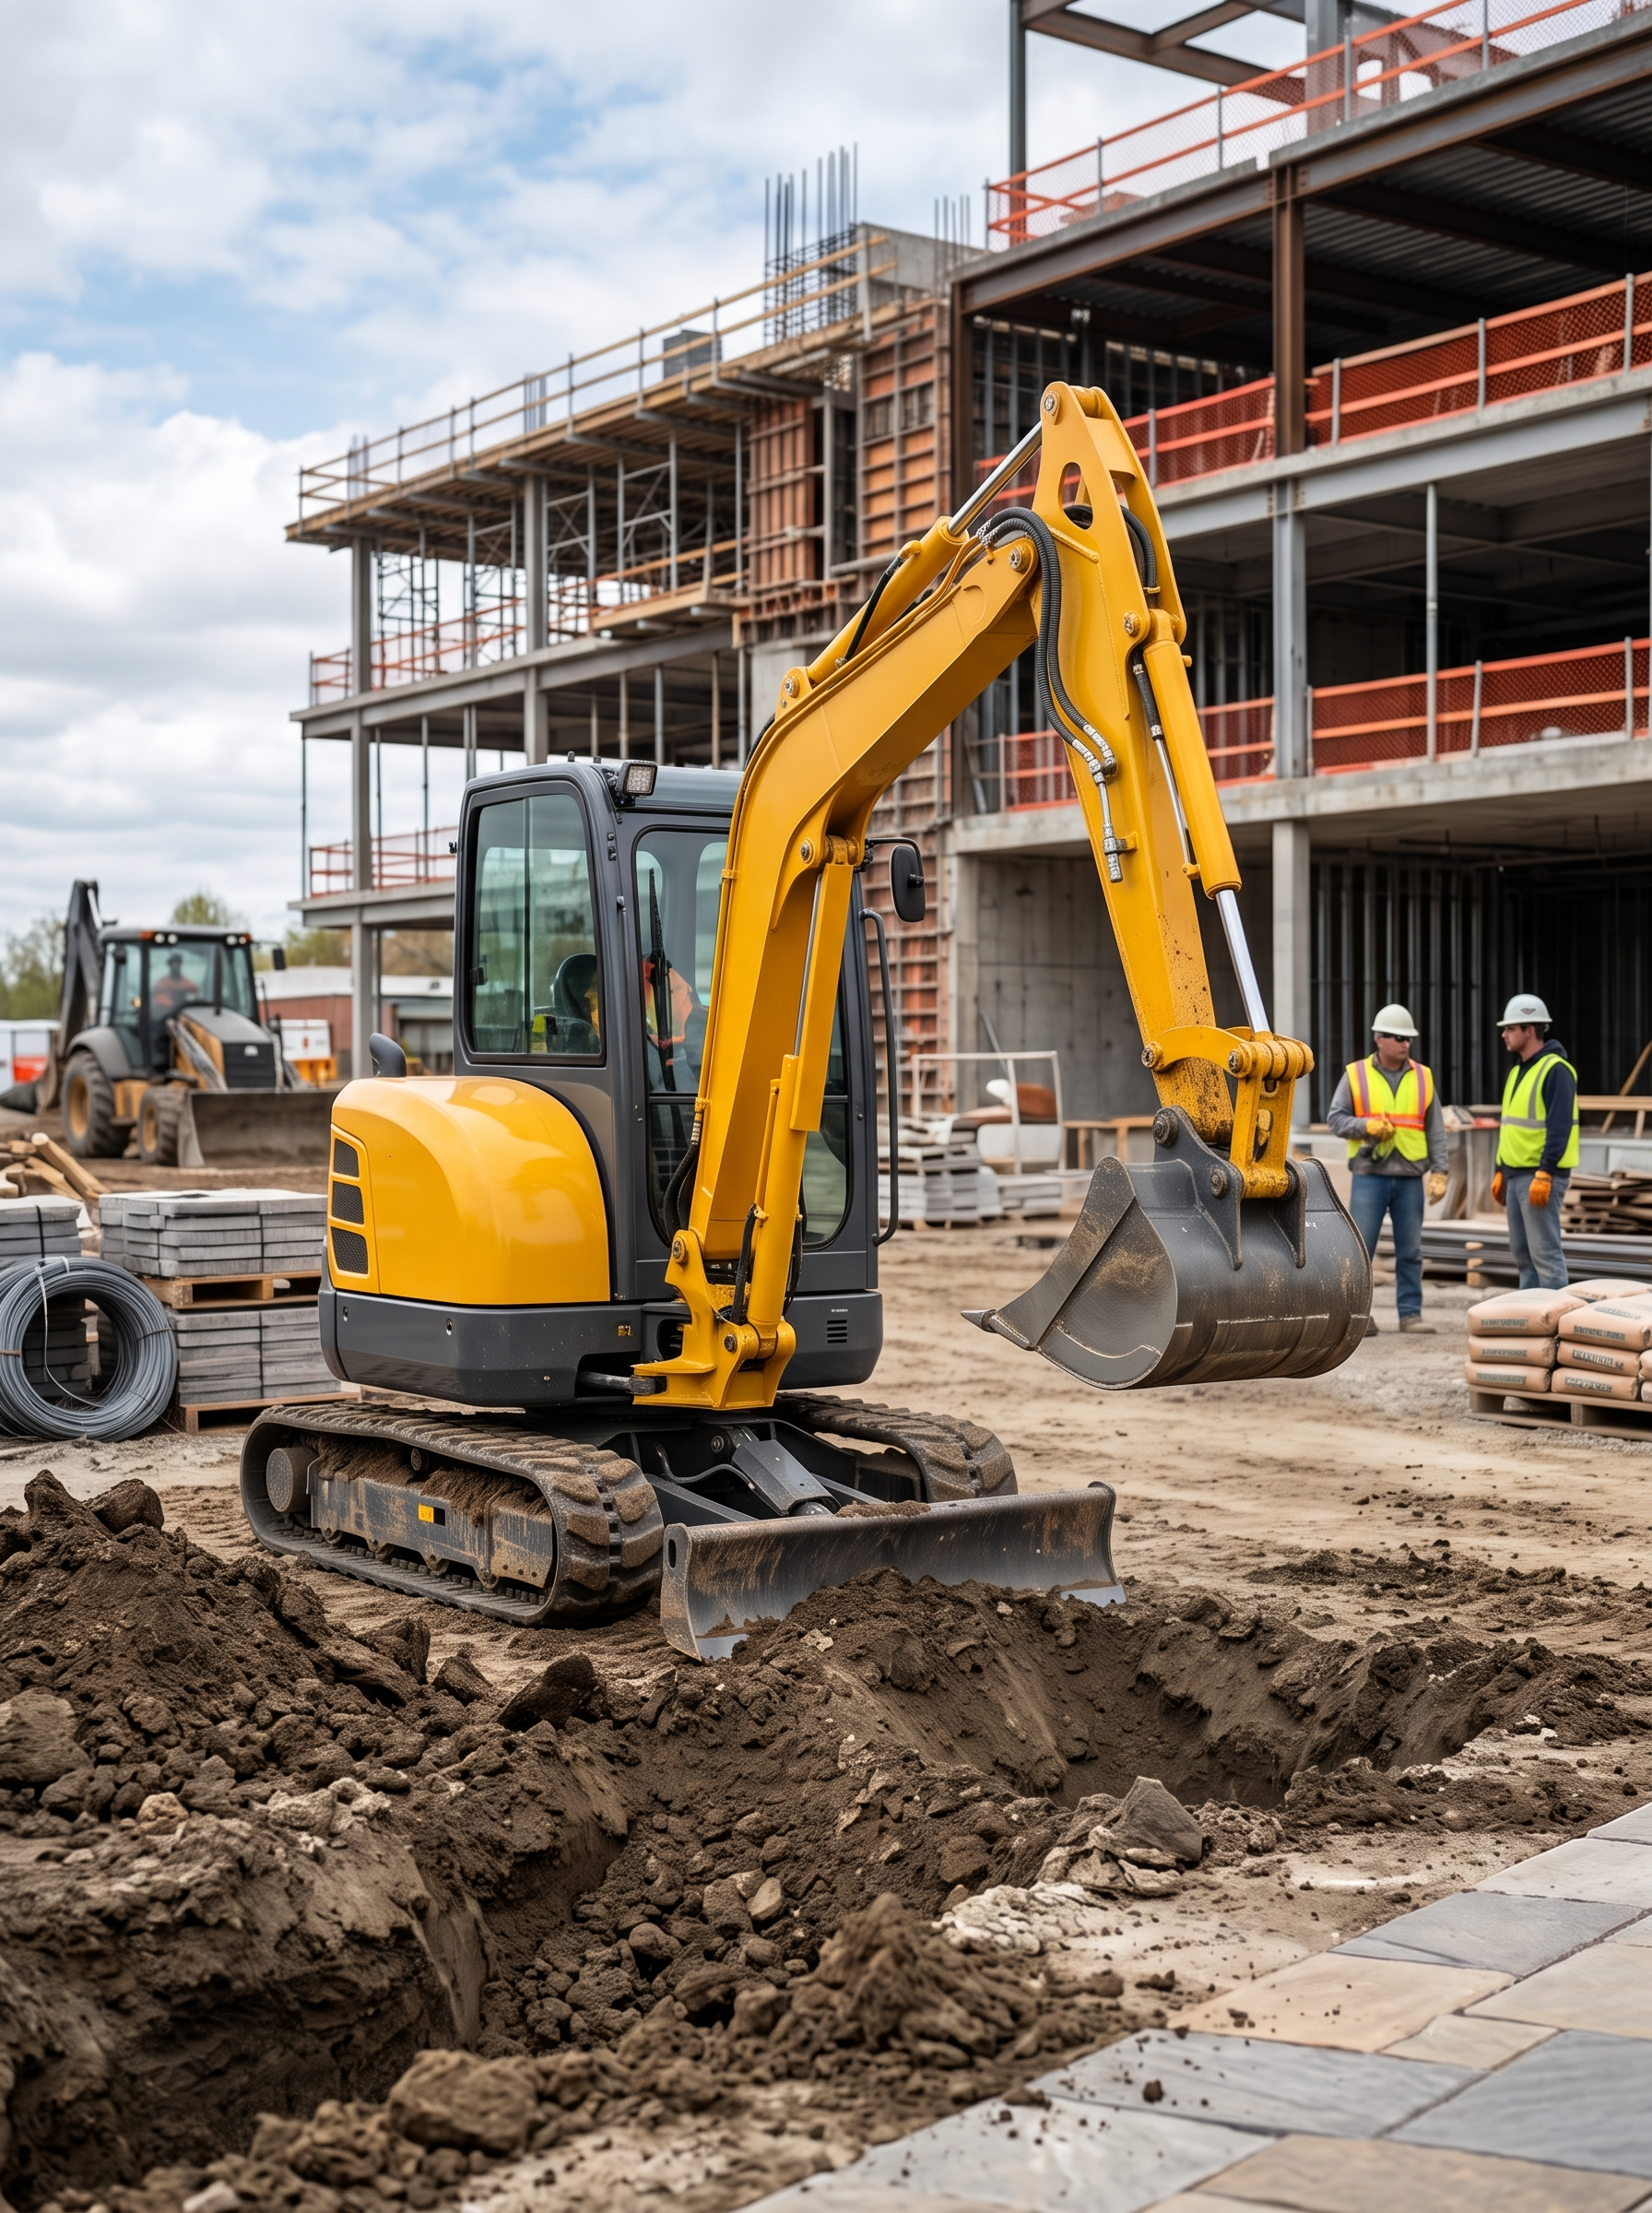
Yellow goods & heavy equipment to keep your sites running. We understand the specific finance structures needed for heavy assets.
Earthmoving & Machinery
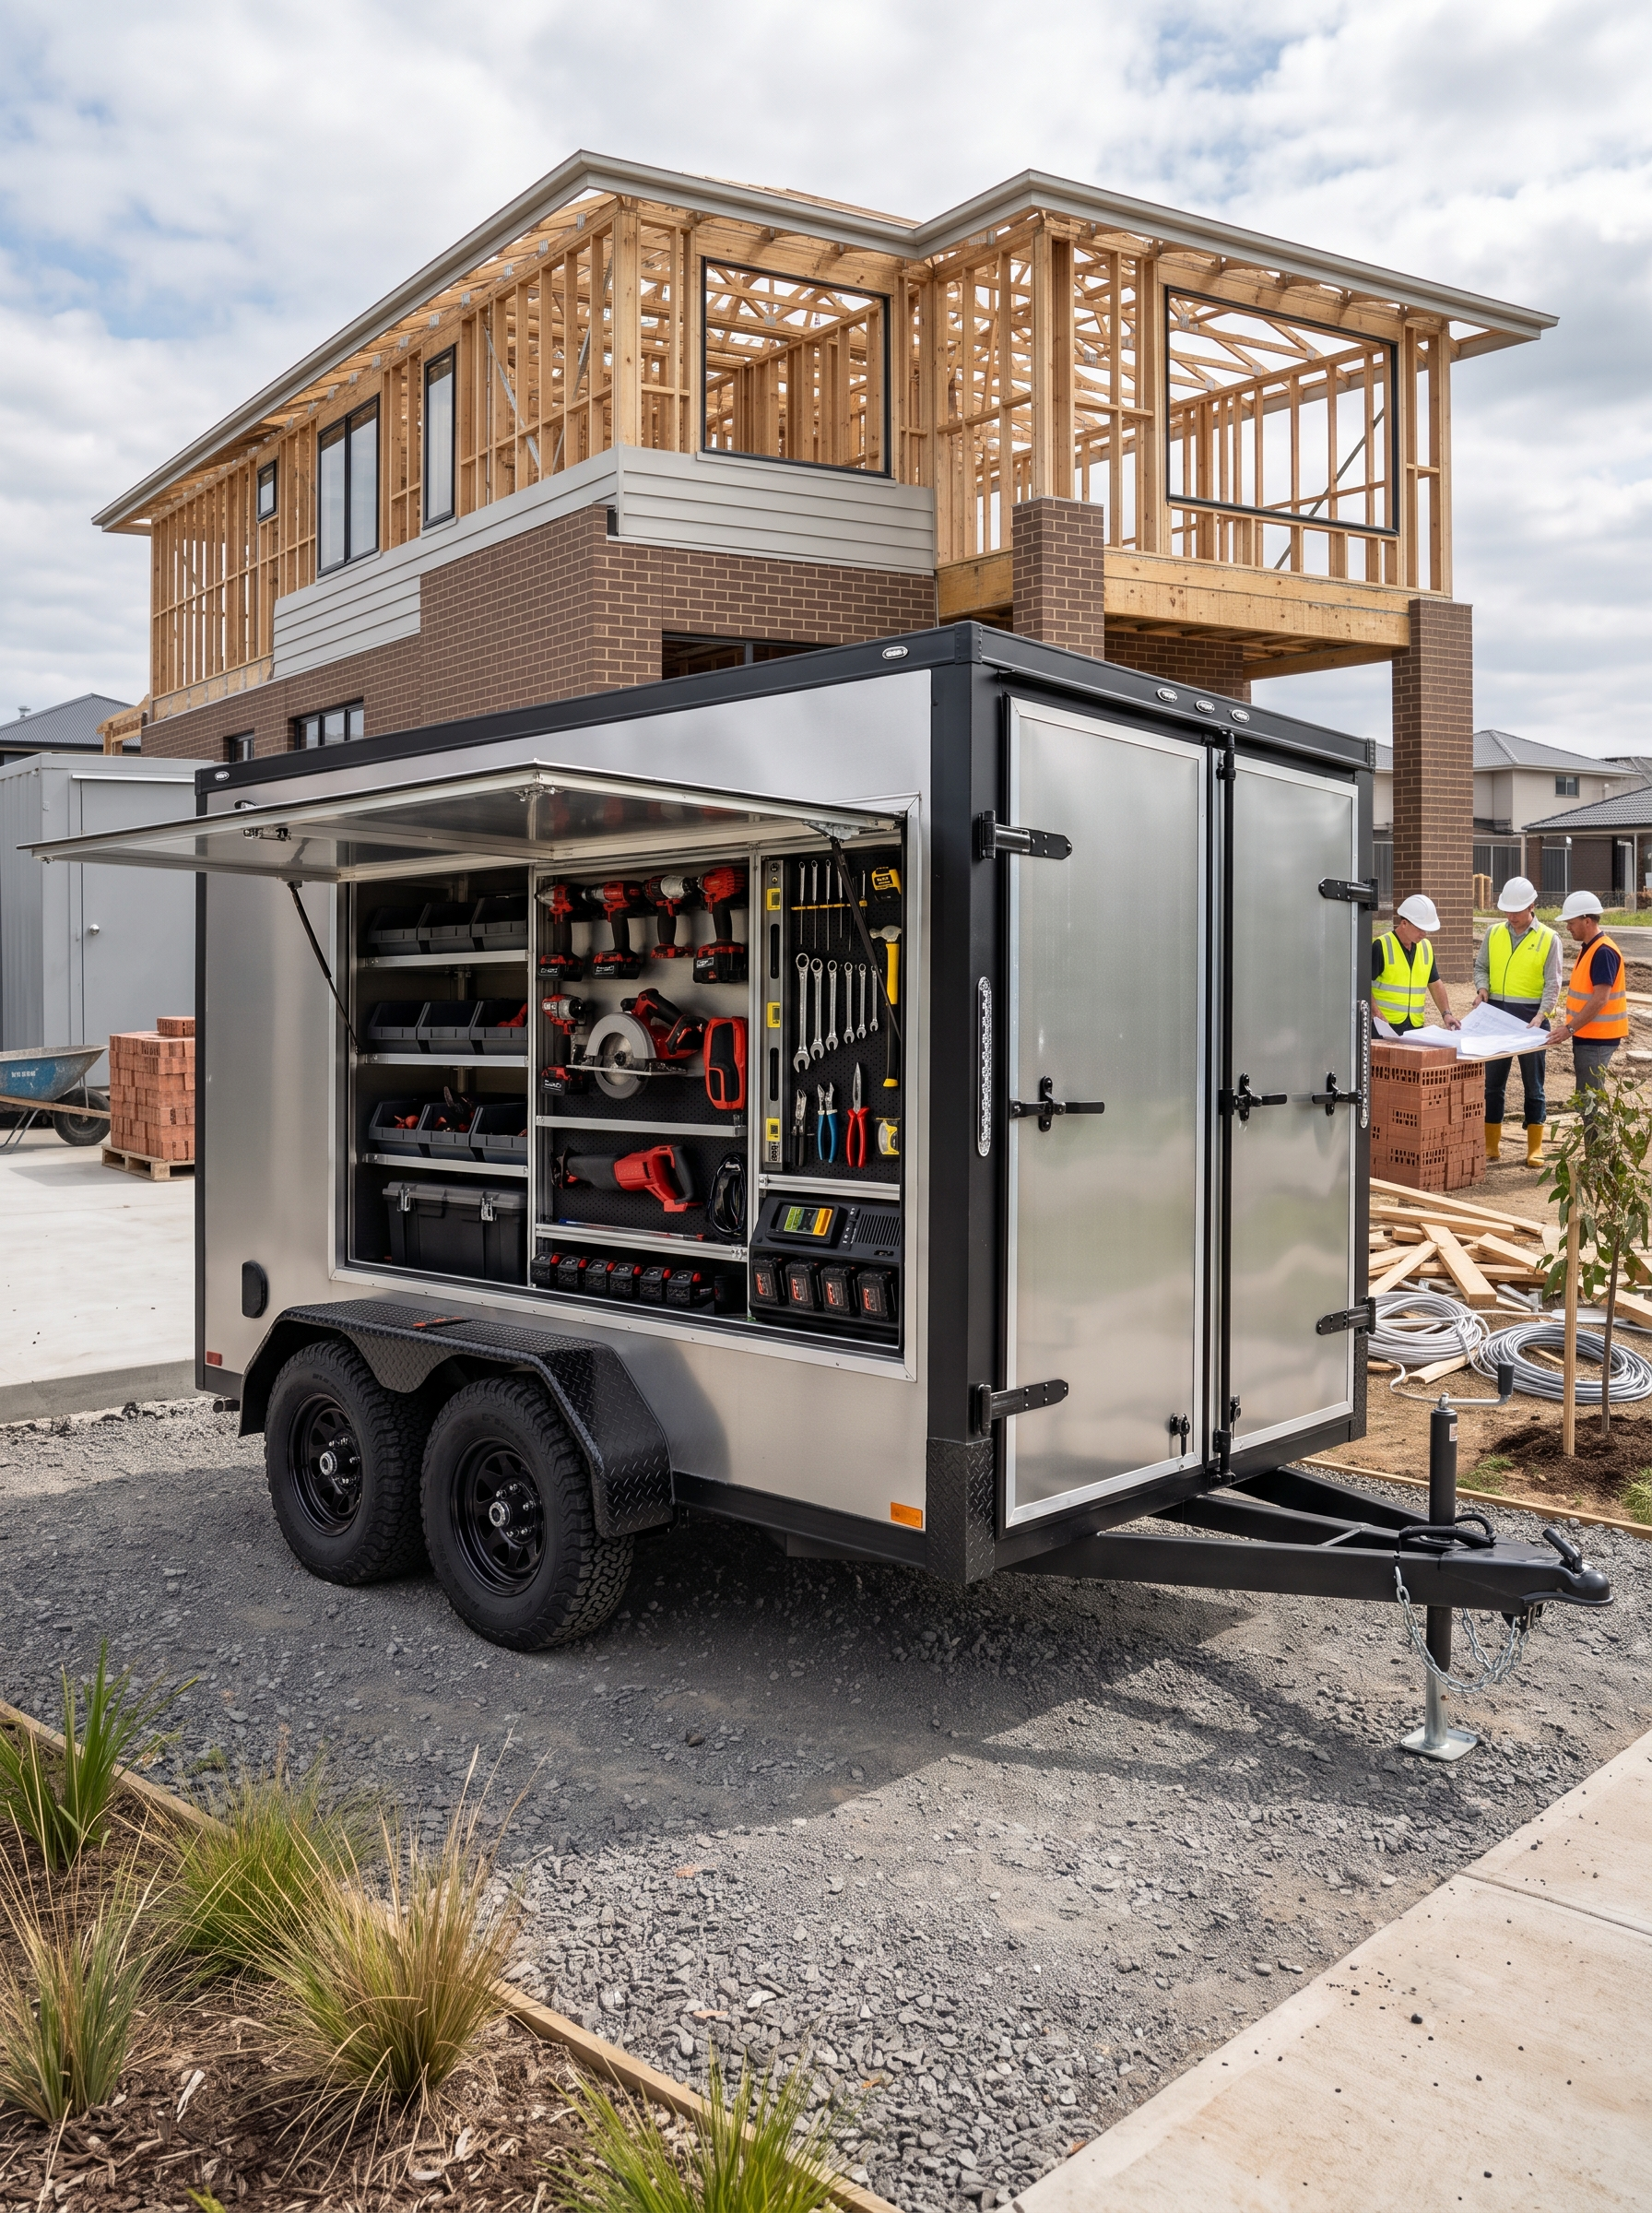
It’s not just vehicles. If you need specialised trailers, diagnostic tools or other machinery for your trade, we have lenders that fund it.
Trade Tools & Equipment
-
Often, yes. With an active ABN, some lenders offer low doc options that use business bank statements or an accountant’s letter instead of full tax returns. Each lender has its own criteria.
-
It varies by lender. Some want two years or more, while others will consider newer ABNs, especially if you’ve worked in the same industry before.
-
In many cases, yes. We run a PPSR check on private sales, and the lender pays the seller directly.
-
A lump sum due at the end of the loan. It lowers your regular repayments, but you’ll pay more interest overall and need a plan for it. We’ll show you the figures with and without one.
-
How GST is handled depends on the finance product and your business setup. Your accountant is the best person to advise on claiming it, and we’ll explain how each option treats it.
-
Lenders usually pay us a commission when your loan settles. We’ll tell you about any fees before you apply, and our Credit Guide explains how we’re paid.